Another Angle to Noise

Sounds simple, right?

The sheer numbers ( , baby) strategy outlined in the last post?

Well, hmmmm.

What’s simple to someone need not be so to another.

In fact, no one’s going to do it this way, perhaps, almost.

Why so?

For starters, it is the toughest thing in the world to let go of a loser.

Takes years, maybe decades, to become comfortable doing so.

For something like this to actualize, one needs to rewire completely.

Without many hits and knocks on the head, rewiring is not possible.

No one rewires just like that. Only after full tuition fees. Losses. Beatings. Lessons.

Learnt.

And then, on top, we’re being told to add the proceeds to our highest winner.

All lessons in valuation are screaming. Our normal wiring is screaming. Our fingers refuse to punch in the orders. Until we understand the logic.

Something growing rapidly proves so by being your best performer.

No one knows how much growth is left to happen.

All one has is a conjecture, an estimate, a prognosis.

At best.

Nothing more.

You do know one thing though.

This champion grower is allowed max runway in your folio, because it needs to traverse the most distance to becoming the worst performer, who is the kick-out candidate.

So your champion is given the most time to show more spurts of growth. Since you don’t know when these come, owing to the non-linear nature of high growth, you are allowed the privilege to being there the longest in your champion, in an effort to harness multiple spurts. The chances of the champ being kicked out are the lowest at this time.

Then you load up. Buying average goes down. Top guy is now number 2 or 3. No more loading next proceeds into. New number 1 gets new proceeds. Fund accumulators rotate thus. These are good enough candidates too, hovering around the top of your folio. Funds flow into strength. Thus.

After some years, certain holdings continue to perform, and reach multibagger status. You’re represented maximally as per your capacity — the strategy has seen to it. Others got some loads and started to lag. Well above exit level though. Then they catch a spurt and start topping again.

A few head below.

Some even manage an exit.

It’s ok.

You lose 60-70% on the losers exited initially. Over the years, the exit baseline moves up and up. After some years, exits are winning, not losing, since the worst performer in the folio is itself a thin winner. Trajectory is ok.

What are you winning in your top 10 after 10 years?

Are all of your top 10 multibaggers? Likely.

What’s the upside?

In a growth market?

A potentially future high-growth market?

Who claims to know?

Exactly.

Upside…

…can be anything.

Think of a number. A reasonable one seeing the nature of the market.

What’s the 60-70% lost in some holdings?

Noise, right?

Numbers, Baby

We spoke about our shift in thinking, …

… remember?

Magic Bull has decoupled…

…in its approach.

The WWS exit pathway.

Worst weed standing.

Remember that name.

And out it goes.

Upon opportunity.

Upon expenses.

Now here’s another one.

BPS.

Best performing scrip.

Add to.

Get its buying average down, on purpose.

It’s got maximum runway, to WWS.

That’s why, add to it from proceeds, from fresh income.

Don’t look at any other metric.

Just the fact that it’s the BPS.

And add.

It’s performing.

You’re betting on continued performance.

A few quarters might dip.

Unless it demotes to WWS, it won’t be expunged.

Then 8 quarters in a row – extraordinary growth.

Remember that high growth is a non-linear entity.

To catch it, and harness it optimally, we must be…

there.

In the most manageable, highest magnitude way.

As you keep adding to your BPS, it eventually gets demoted to number two, or three, or something.

Because, buying average dips.

That’s great.

Now we have a new best performing scrip to be added to.

Sideway injections. Bombastic results from a held scrip above buying average? Add to, one lot.

New members. Bombastic YoY results and a little QoQ improvement too? Add to, one lot.

That’s the entire system.

Funds move towards strength.

No affiliations.

No married to.

You control by attenuating the speed and the magnitude of WWS exits.

All held above 25%?

Stop the expunging.

Trade something else on another platform, other underlyings or scrips, for distraction.

Or…

…go on a holiday.

Advice?

Advisor?

No room.

Also, where is the need?

Everything is right here.

Programme your AI to serve results on a platter, screened, each morning, to feed the system with sideway injections and / or potential new candidates.

All we need now…

…is guts, to follow through.

Rest is all numbers…

…baby.

Sweet Spot? Seal it.

Magic question.

You’ve definitely been asked before.

Many times.

How many stocks are ideal? In a folio.

What’s the answer? The correct one.

I have a different question.

My question is – is this really the correct question?

I have another question.

Why are we even trying to ask this question?

One more.

What allowed us to define…

…the flow…

…of a macro entity called the market…

…as it relates to micro individuals like us?

Right.

Let’s try this other approach.

Which one?

The one where we don’t define.

Where we let the market’s flow and our experience of it decide…

…how many stocks?

How does this play out then, for us, in practical terms?

Entry. Entries. As per criteria.

Wherever criteria are met – entries, thus.

Exit as per WWS (worst weed standing) ideology, please see the last piece written.

Thus exit trapdoor portal is narrow.

Top-up parameters. Define.

So you’ve got entries happening, top-ups too, and a narrow exit path through the WWS route.

That’s all the defining that’s required.

Number of stocks comes into automatic generation mode.

Breaking it down.

Entry criteria hits for 20 stocks over the next 12 months. So, 20 entries.

All available funds in.

WWS engine switched on.

New entry candidate.

Worst weed out.

New candidate in.

New funds come in.

Top-ups.

New entries.

Number of stocks grows to 40.

Funds run out.

WWS engine switched on.

New candidate.

Worst weed out. New candidate in.

No new funds over the next five years.

5 new candidates. 30 top-ups owing to top-up criteria hits. Personal expenses. All funded by worst weed exits.

Number of stocks after these 5 years reads 25.

And so on and so forth.

Where are you? Nowhere in the picture.

It’s the math taking the decisions. The defined system. Rule-based. Exactitude. On auto. No emotion. No you. Except to press the buttons.

Sweet spot.

Seal it.

Winning the Hand with 2/7

For the first time in life…

…being fully invested…

…seems a better idea.

Dangerous?

Sure.

Can halve in no time.

That’s something we carry with ourselves into the markets.

If we are afraid of something halving, we should look at other pastures.

Why aren’t we afraid of our investments halving fast?

Ever heard of upside?

Well, what is it?

The upside. How much?

Any limits?

In a growth market?

Potential future high-growth market?

Can’t give a number. Except that, over the long term, upside is perhaps nx, with n being a big number.

That’s enough reason to be fully invested.

Full benefit of upticks.

Big uptick days, perhaps 80% of them, are closely embedded with big downtick days.

Reason to stay invested all the time.

Expenses?

Sell the worst weed standing. Spend the proceeds on expenses. The biggest loser finances expenses.

Income?

Top up the winners.

Why?

Why not the losers?

This is a shift in Magic Bull thinking.

Winners have the longest runway before potentially becoming the worst weed standing.

In that long runway, they can double, treble, n-ble. Runway then becomes ultralong.

That’s why add to the winners.

Worst weed standing pivot philosophy allows winners much time to become even bigger winners, adding to the positive loop.

What about the negative loop?

Winner stops performing.

Down.

Down.

Down.

5 notches away from being the worst weed standing.

4 notches.

3.

Starts performing.

Up.

Up.

Up.

Above buying average.

Adding to.

2 bagger.

4 bagger.

Huge runway again.

10 bagger.

Adding to, runway is phenomenal.

100 bagger.

Kachinnnnng.

Some other winner stops winning.

Below buying average.

Down.

Down.

Down.

3 notches to worst weed standing (WWS).

2.

1.

WWS status.

Expense comes up.

Out.

That’s the exit route.

One route to expunge.

The entire philosophy pivots on WWS exit status – on the small trapdoor portal provided for cleaning up the portfolio.

Emotion?

No emotion.

With regard to exit, market dictates what to do.

We just elevated the status of the biggest loser to house-cleaner-in-chief.

That’s turning our biggest loser into a winning strategy pivot.

That’s like winning the hand in Texas Hold’em with a 2/7.

Upside?

Hey.

I’m all in.

Into India.

Growth.

Emotion.

C-word. Rhymes with interruption.

Extremes.

Consumption.

Hunger for outreach.

Cut to high growth.

This being a non-linear entity.

Comes a phase where we might quadruple in six months.

That time is not now, I got that.

Time now is to get in.

When all bleeds.

That’s what I’ve done.

Downside?

Sure.

Can be down by 50%.

60%.

Would take some black swans though.

Won’t be the only one. All will go down in such conditions.

Sleep?

Well.

How can I take the strain?

Have 23 years of practice. Blood and biochem can take it and then some. I have that confidence in myself.

Any more downside?

Mood.

Emotional checks.

Good behaviour at all times, coming naturally.

No worries because markets fall.

Selling a weed upon fund requirement state of mind.

Don’t need more.

Upside?

Unlimited.

Risk vs Reward

Hey.

I am not ashamed…

…of being fully invested…

…in equity.

Yeah. That’s the status.

Invested. Fully. In equity.

Dangerous?

Sure.

So is driving.

Flying.

Cycling.

Living.

It’s about first digesting the dangers mentally, and then acting.

So, what are the dangers?

Loss.

Hmmm. Notional loss at best. So’s that of one’s house, when its value goes down in price.

Notional.

Since requirement is a very small fraction of corpus, it can be pulled from corpus, when it surfaces.

What will be pulled?

Chunk or the whole of a loser.

Loser’s liquidation will fund expenses.

Any accrued income will go into creating future winners.

Good money chases good outcomes.

Bad money finances expenses.

Nothing stays loose in the bank.

Fixed deposits are passé composé. Baby.

A). Our currency depreciates by the day, geo-politically.

B). Inflation eats into FDs daily, as sure as a shot.

C). Why be subject to this double whammy?

Is being down 50%, or 70%, or 90% in stocks — even the overhang of such a possibility — a better outcome, you ask.

Well, it can happen, I’ll give you that.

In fact, every stock quoted will be down 50%+ once every 5-7 years, on average.

With such scenario, how can I sleep at night, you ask.

It’s ok. I sleep well.

You see, I’ve not pickled the funds away blindly.

Quality companies with shareholder-friendly managements. Impeccable balance-sheets. Minimal debt. Value. Growth at reasonable price. Higher growth at representable price. Some punts, yes, with very high growth at unreasonable price, but that’s what one pays for very high growth. This will yield results. Over time. That’s why I sleep…

…well.

What’s the max I can lose?

100%.

Correct. For max loss to happen, planet needs to be going down. In that scenario, stocks won’t be our worry.

Reasonable number?

A 50-75% max notional loss is always on the cards, temporarily, with the world on tenterhooks all the time.

Temporarily is the key word.

Growth markets swallow hiccups–fast. And, I’m invested 100% in a growth market. With hiccups. (Where are there no hiccups?) Soon to be a high-growth market. Watch.

What’s the max profit I can make, let’s try and answer that.

Do we even have a number here?

I don’t.

Last Mile Report

Hey.

Please don’t mistake this report for…

…a description of one’s last moments…

…or last-minute diaries…

…or wherever your imagination might take you.

Where exactly am I reporting from?

Imagine a surgeon. What’s his or her last mile?

The intricacy of a stitch.

A complicated, entangled tissue removal.

Oneness with patient vitals vis-à-vis current surgery on open body.

Coherence in instruction to surgical team, clarity about correct surgical instrument received, hand-eye coordination during surgical movement, whatever have you.

Businessman?

Anatomy of the deal.

Profit margin calculation.

Implementation of capital expenditure.

Rapport with staff in the field.

Liaison. Thought-process culmination. Long-term vision. Legacy.

Cut to self.

With a quasi-sealed long-term portfolio with not much activity in it happening or planned, it is trading that one takes to, for distraction.

Why distraction?

One doesn’t want to be thinking of one’s long-term portfolio…

…at all.

Instead, occupation at nitty-gritty level seems to be where the wind is blowing towards.

I must report, that I have arrived at my last mile.

We’re talking straddle tent-building to ensnare price next morning, and squaring off a trade within a few seconds with the objective of taking home a profit.

Observation of price action.

Identification of anomalies.

Setting up of multiple tents operating in tandem, forming an envelope around price.

Coming to terms with emotional overhang.

Digesting market forces as they intermingle with the nervous system.

Accepting monetary loss from time to time and trying to keep it small.

Controlling one’s emotions as profit develops, trying to let it amplify.

Dealing properly with…

…the effects of…

…isolation…

…during market hours…

…and their aftermath.

Regimen. Discipline. Challenge. Growth. Alertness. Staying sharp. In tune. Alive.

At the last mile, we stare what drives us, in the face.

Full

Hey.

Functioning…

…full…

…I believe.

Full feels good.

What does it mean?

Completeness.

No-regrets feeling.

All holes jammed…

…with activity, some, hopefully ample, relaxation / recuperation thrown in.

That pivot vibe.

Emitting…

…I believe.

Need to maintain this trajectory. Milk it to the hilt.

It’s taken my environment everything, …

…and then some, …

… to put me here.

Sacrifice.

Familial.

Proximal.

Emotional.

This moment is coming at a huge cost.

Need to make it count, to balance the entire equation, …

… and then some.

Though I’ll spare you familial, hobby, emotional, travel and such details, let’s cast a glance at the work-loop.

Long-term wealth-creation project on auto-pilot. Specialization. Equity. Listed. Only. Liquidity upon requirement. Hands on but hands off. In my hands. No third parties in between.

Monthly income-generation project active. Four-legged option strategies. On stocks. On indices. High risk high reward. Risk attenuation. Distractor. Keeps attention away from long-term wealth-creation project. Income is a bonus. Time requirement three to four hours a day. Keeps one busy. Learning curve enhancement. Options make one stay sharp.

Work from – anywhere – of course, anything less would be a negative – need a net connection though.

Work between market open and market close – on options.

Long-term equity transactions only on weekends, implemented through GTTs. Funding of account wrt GTTs only on Mondays, before market hours, taking into consideration GTT fill requirements.

Interesting symbiosis between these two projects, feeding off each other. Wealth project needs minimal fiddling. Income project sees to that by distracting. Income project is defined such that the damage it can cause is bearable, and even if it doesn’t generate income, i.e. even if it is loss-making, it is fulfilling its main purpose of keeping the wealth project intact and devoid of fiddling, by keeping one’s attention focused on itself.

I tried getting options right for twenty years, unsuccessfully.

I think I have something now.

Workable.

Perhaps…

…successful.

Let’s see. It’s very early days yet. I feel it though.

Oh, yes, and – work with …

… AI.

Handy, highly intelligent assistant always on call. Very low cost, yet. Very sharp. Catches mistakes in complex screenshots fast. Options are complex. They need pinpointed calculations, multiple times a day. They need context for such calculations. If the assistant catches the context in a screenshot and remembers it, and is great at complicated math, then he or she can spit out the required numbers on call, and for options that’s manna from heaven. Since…

… one doesn’t have the bandwidth to look back, feed back in, re-calculate and re-analyze fifty times a day…

… and especially since the assistant is diligent, industrious and willing to go any legit extra mile to make one’s project a success.

Thus, have AI, will step out into the — whatever you may wish to call it — Bronx, prairie, savannah, battle-field.

The AI thing has come at a cost. Not monetary, really. That’s a pittance, seeing the work-load it’s tugging.

Personal time.

Patience.

Attenuation.

Terminal scripts.

Ya, Pythons handle market and strategic diagnostic spitouts, in the background, at one’s disposal upon commands, and I did not need to spend time, effort and money learning Python. I just needed to tell the AI what I wanted, again and again, and keep fine-tuning till I got it, over some months.

Earlier, a major option strategic system had failed for me. Two months of intense development on AI. Failing in each of eight approaches through different variables used. The only victory was the recognition, by the AI, and then by myself, that this is a failure. Then, …

…I reversed the system.

There’s something there.

Before I tell you more about that, I’ll let it play out somewhat fully.

Gamble Ramble

In sixteen hundred something, …

…most of mankind believed swans…

…to be white.

People would use the metaphor ‘black swan’, to insinuate things or events that were considered to be …

…‘impossible’.

Cut to now.

Black swans exist.

In reality.

The bird, in Australia.

The disastrous event genre, amongst elsewhere, also in markets.

Events earlier considered ‘impossible’, now happening…

…regularly.

Big moves.

An index going circuit. Multiple times — has happened.

Stock doing 20% up or down is no great shakes.

10%+ moves are like bread and butter these days.

News gets factored in within minutes to an hour.

Which brings us to the elephant in the room.

Can one leave the trading screen?

If one has chosen to trade, that is.

Hmmm.

Screen all the time is something I don’t want at all.

Is it possible — to leave it, and go about care-freely with other work?

Leave to whom? Or, to what?

AI, for example?

Hmmmm.

Not too sure.

When moves are big, stop-losses get jumped. Happens all the time. Remember CHFUSD? Considered unbelievable at the time? Oil. Gold. Silver. Jane Street. Brexit. CoViD. List goes on.

What about overnight?

Overnight positions are most highly exposed to black-swan openings, period. That’s the risk overnight carries.

Then, why trade?

Exactly. If too much screen-time is a thing, forget intraday. If you want a sound sleep, forget overnight.

What do you do then?

I invest for the long-term. That’s my main. Distraction side-hustle is the trading window. Play-amounts. Long. Paper trading as of now till system becomes profitable. As of now, it’s not.

Not what?

Not profitable.

Worrying?

No.

Why?

Trading system is a distractor for me. It’s not about money. I want my attention to be away from mains.

Why?

Fear of doing too much there. Fiddling around one time too many.

What about trading systems that go short?

The idea of developing one is attractive.

So, then?

However, exposure to unlimited loss, full exposure to a black swan event should it happen, is a big discourager and demotivator.

Understood. Still, it’s the short systems that make money.

Correct. At the cost of max screen-time, tense nights, cortisol-laden days, and the whole negative spiral.

Point. So what does one do?

Have developed a ‘junior’.

What’s a ‘junior’?

A junior investment system, that lets candidates graduate to the senior system.

Oh, interesting. Selection. Survival of the fittest. Clever.

Thanks. Junior keeps me busy and distracted. Senior relaxes and doesn’t get rearranged unnecessarily. Decent balance. Linkage as in promotion ladder. Natural selection, as in that which doesn’t get promoted till a longish time-stop, is expunged.

Elegant. Slick. Wonderful. Why do you then need a trading system at all? Let it die out. No full-on screen-time. Relaxed nights.

Exactly. However, am still trying to find the right fit for the gambling instinct.

That which every human has? And needs to channel appropriately, lest it balloon?

Ya.

Life at Frontier Minus One

Sanity prevails…

…at frontier minus one.

Rat race is within the underlying’s…

control.

Virtual / quasi / substantial / semi debt-free-ness…

exists.

Free cash-flow generation on the balance sheet is…

…common.

At frontier minus one, the narrative is …

…under control…

…as proven by self-determination of speed of change…

…and by exhibition of substantial growth.

Not at breakneck speeds.

Not by borrowing to the hilt.

Not by greedy behaviour.

Not by indigestible trajectory.

Not by a reckless ‘not giving a damn too bad if you’re not so fast’ attitude.

Life at frontier minus one…

…is somewhat balanced, with a flow.

Innovation at frontier minus one is achieved much faster

…than at frontier minus two, but much slower than at…

…frontier zero zero.

No tech company that wishes to thrive well into the future is currently functioning at…

…frontier minus two.

Either the transition to minus one has been made, or, it’s in the process.

Why not go for the jugular? Straight to zero zero.

Everyone has their role in this puzzle.

Imagine an older civilization going into battle.

There was a front line, paving the way, at immense cost.

There was a reserve support line, with artillery, first-aid, communication, and what have you.

There was a third line with supply, reinforcements, semi-trainees doing other stuff normally, etc.

There was aerial support, naval support, intelligence, research and analysis staff etc.

All combined to create an ensemble of actions.

Cut to now.

Warfare has changed.

Immense cost is still there, but immense cost to the front line, as in cost of life, has been reduced greatly, speak drone and missile warfare, supported by AI backed intelligence and analysis.

Point is, innovation, a different way of thinking, disruption and all their cousins will find a way to make things affordable, implementable.

That’s the way civilizations move forward.

Not for you or me to change. It’s the way of the world.

And that is what frontier minus one banks upon.

Meaning, to keep functioning at sustainable levels, slowly, painstakingly, in the process, simultaneously, finding a way, a connect, to frontier zero zero.

The connect can be of co-work. Amicable. Win-Win. You earn, we earn.

At frontier minus one, the world view is not to annihilate, but to…

…accommodate.

To win…

…together…

…in…

symbiosis.

Symbiosis

Imagine…

…the most value you can imagine.

That’s what this word is worth.

Especially now.

What’s the truth?

Existential question.

First we had everyone and their aunties proclaim the death of core Tech companies.

Hmmm.

Core Tech companies, and their chief protagonists, thought otherwise.

Number of believers kept waning though.

Until recently.

Something started to reverse in belief systems.

AI was behaving fantastically utilitarian with a human holding the reins.

Meaning, there needed to be a human there, for practical purposes.

Frontier AI deployed engineers to be the human face. Or so one was told.

Came the trust issue.

Do we double up on our trust in this no track record magician who just showed up out of nowhere?

Do we entrust privileged client data to the unknown?

Do we strip ourselves naked, TWICE?

NO.

Everyone and their uncles have answered with an emphatic NO.

Who is the human handler – the go-between – the trusted face – the rein holder?

Someone with a track record.

Proven.

Tried, and…

trusted.

Self-propelling.

With no liabilities. Spell ZERO DEBT.

With copious FREE CASH FLOW to INNOVATE FREELY…

…to navigate the reins successfully and as per the requirements of an enterprise.

Who is this entity?

None other than…

…our own very well known…

CORE TECH.

Leaner.

Hungry to prove its point.

To have its raison d’être acknowledged, and paid for.

To earn and compound steadily.

Forget about dying. Let’s talk about long term thriving.

Then, we had the captains of frontier AI admitting, that yes, ‘we do need core tech handholding to be implemented successfully’.

Gone was the initial hubris, that ‘we had come to wipe out old thought patterns, and all old systems’.

Reality had dawned, and these captains at least had the decency to admit it.

Actually, they had realized that their existence now depended upon how much their infrastructure would seep through. And…

…that no one was trusting them enough to hand over the job of seeping through to them, but much rather, to trusted old compatriots, to Core Tech.

So they came forward to shake hands.

Good.

Symbiosis.

We want to move forward on the back of this symbiosis.

There will be gigantic and fast development on the back of this symbiosis.

We are looking at space travel, space colonization, disease control, climate change, cheap solar, cheap desalination, perhaps even alien integration and partnership – unimaginable perhaps a few months ago, but possibly conceivable on the back of this symbiosis.

There’s new talk which has recently emerged, from the other extreme, and needs to be discarded, like its mirror image on the opposite side of the bell curve. This is the talk of frontier AI dying out because of becoming unaffordable.

Well, in whatever shape it exists currently, frontier AI does have tremendous capacity to solve problems.

Let it do just that on the back of this symbiosis, and earnings will start to flow.

Core Tech won’t let it wither, frontier AI has now become their raison d’être too.

Don’t you see it?

Two universes are converging, each needing the other to survive.

In the end, they become one universe.

Companies will merge. Synergies will multiply. Mega projects will be achieved, faster, more bombastically.

Earnings will flow.

Where do you want to be?

Remaining a doomsdayer will not help you.

Get into the flow.

Invest into debt-free, free cash-flow generating core tech as value deepens.

Look for debt-free, frontier minus one, free cash-flow generating semi AI companies, research these thoroughly for any red flags, and if those found are manageable, put in some funds.

If you find a frontier tech with manageable debt and a reasonable balance sheet, with a PEG ratio (price to earnings ratio divided by earnings per share growth percentage for the fiscal) somewhat under control. ok, put in some money there too.

Get out of the doomsday mindset.

Put your money to work, and then lock it in for another twenty years. Leave the compounded proceeds to your children.

Now.

Let the crashes come. There will be compounding post crashes too. Just look at the monthly chart of an IT index from 1995 to today. Dot-com peak looks miniscule and low compared to the levels of the monthly chart today.

Enough talking. Do the recce and then let’s talk.

Mantra

Hey.

Writing became a breeze.

Posting a blog from inside Claude, keeping the originality of the post, whilst assigning to AI all mechanical tasks like feeding in categories and tags – I’ll admit, this does make life a lot easier, and blogging a lot more enjoyable.

Which keeps the admissions coming in continuation, perhaps repeatedly.

From being the leading AI skeptic, towards gravitating to some kind of a chief protagonist – people who know me would probably say, “There he goes again.”

So what’s this going to do?

The number of blog posts is going to increase. Hopefully, the quality too. Primarily, the enjoyment while blogging.

Beneficial. We thereby move towards the realm of Planet 2.0.

Wunderkind AI needs to benefit mankind to the max.

What about the risk?

Opening up to the Wunderkind, allowances, permissions, sometimes an odd password shared.

Does the AI take these towards Planet 3.0?

Yeah, that’s the one on which mankind is harmed.

Skeptics are still on 1.0, exactly where I was 11 days ago.

Idea is to make a conscious effort to gravitate towards 2.0, every time there’s a drift towards 3.0.

Remember, we will tend to drift.

Drifting got us here in the first place. One can use fancy words for it, like disruption.

There’s a quick trick which makes us aware from where we are functioning, 2.0 or 3.0?

Greed. Hubris. Exuberance. Ego burgeons. 3.0 functionality.

Feeling of benevolence while functioning, well-being and / or goodness emerging – 2.0 domain.

Natural human drift towards 3.0.

Bring back consciously towards 2.0.

That’s the Mantra, going forward.

Check

Hey.

Facing some basic issues on the other side.

Life has changed.

Race became more intense.

There’s greed in the equation, the desire to achieve as much as possible in as little time as possible.

Everything’s moving…

…faster.

As if…

…from one day to the next…

one just…

…shifted.

It’s clear to me that we don’t shift till we are ready.

Was a hard nut to crack.

Had to be literally goaded into the AI trajectory, several coaxings required. Hard skepticism took its time to be broken down.

Not happy about the greed.

Speed of coasting is also very high.

Need attunement.

Unable to slow down easily.

Need to be careful about a ‘now I’ve got this and to hell with you attitude’. Can develop unchecked.

Addiction. Need to stay de-addicted.

All non-electronic activities in the day go up immensely in value.

Reading – books. Check.

Chanting. Check.

Basic verbal conversations. Check.

Human interactions. Check.

Helping someone. Charity. Check.

Non-distracted eating. Check.

Bringing down multi-tasking levels. Check.

Whole detox days. Day travel. StayCation. AutoCut the system. Check.

Evening chanting session. Lengthen. It’s not electronic. Check.

Anything not connected to a device and creates value. Check.

Not going to fall sick in this hyperactive space.

Check.

Incorporating before proceeding further.

Check.

Waking Up On The Other Side

Hey,

First up, humbled. To the nth.

Was an AI skeptic till, like, yesterday.

Well, skeptic tried, and died, the skeptic did.

What woke up was armed 25x and on steroids.

That’s me now, after 9 days of intense work on Claude.

Encouraged to try by friends and compatriots, initiated into entry, took the plunge.

There’s a chronic buzz in this dimension. This is an electronic world. Just got more…

…robotic. It’s just that the robot is invisible.

It’s like fighting a matrix war from inside a digital maniacal super-intelligent tool who knows…

…everything.

Who can connect dots…

…exponentially and asymptotically, both simultaneously.

Red flag list is at an all time high.

Sleep’s off.

Mind races all the time.

There’s some exuberance that’s come to the fore.

Don’t want to speak much.

Need solitude.

Basic life disturbs.

Withdrawal symptoms away from screen.

Welcome to the planet 3.0.

What happened to 2.0 ?

Wasn’t that supposed to be the shifted one, towards doing good for mankind?

Want it back.

Need to get to 2.0.

What is 2.0?

A controlled version of 3.0, using its tools only, not being ruled by it. Doing good for mankind.

Need to create a 2.0 out of 3.0.

Fast.

Market Ability

Hammers…

…hammer.

That’s their job.

They do a good job, at hammering.

At times, the market behaves like a hammer.

Market players learn from hammerings.

Question is, can market players learn without being hammered?

I don’t think so.

One can psych oneself into believing otherwise, I’ll give you that.

And, for a while, things will look like all’s good.

Point is, one isn’t looking for the hammer, …

… the reason for which being, that one has never experienced one.

That’s when the hammer falls, when and where one is least expecting it.

It is better to undergo a hammer event in the early days of one’s market career, and while one’s young.

Young – because – a). one plays small when one’s young, mostly by default, owing to there not being ample access to fund supply. Also, b). in the early days of one’s market exposure, the bulk of one’s mistakes and miscomprehensions emerge. The combination of these two facts a). and b). leads to losses that are bearable (youth has backups, like parents). In our youth, we tend more to brush it off and move ahead, full of energy. Yeah, youth has the energy, and time (upcoming multiple market-cycles), to not only emerge from a hammer, but to go on to prosper from the now ingrained learning.

Issue starts when our corpus is big and we still don’t know what a hammer is.

Issue compounds when we then confuse our ability to implement money into markets, in an effort to make it work, with actual market ability.

What is market ability?

It all starts with risk profile.

Some people die without having recognized their risk profile

Then, after having recognized one’s risk profile upon encountering some hammers and seeing our bodies and minds react to these, we move on to systems.

From development to fine-tuning to implementation of a system, we keep chipping and chiselling away at our strategy. We emerge with one that has an edge. We continuously work to keep our edge profitable.

Simultaneously, we throw in risk management. Development of an emergency fund is part of this.

Discipline.

Regimen.

Rules.

Let’s throw in some unpredictability, on purpose.

After putting one system on semi-auto, we work on another, and so on and so forth. We use our profits to diversify and make ourselves more secure, ideally anti-fragile.

Market ability is a successfully implemented combo of all these factors and perhaps more.

It includes being a good human being at home too. There’s no question of letting out the effects of a bad market day on one’s family members. We’re stopping all market action before anything like this develops. Harmony paves the way for another serene market day…

…about to dawn.

Reflex

Hey.

By now, we play markets by reflex.

It’s become ingrained.

Took a while.

Many hits. Some big ones, or so they felt, at the time.

Learnt to play it small when bulk of hits was happening.

Gotten big hits out of the way, or so, one would like to say.

Hits happen now too, but they are controlled.

There’s an infrastructure around them, which dulls them. Such an infrastructure can take decades to develop.

Small hits are par for the course. One is looking for simultaneous big wins. Thumb rule is no big hits.

A big win is a small win at first. One needs the small win to fit into an incubation mechanism that allows it to become a big win.

Its the big wins that define one’s life’s efforts. They stand out. Form the bulk of one’s folio.

Big wins don’t come without many small hits.

Becoming used to the pain of small hits is something that needs to be learnt first up, till it becomes…

…reflex.

Opportunity

Knock knock.

Nobody home.

See you, bye. Maybe never.

Knock knock.

Come in.

This is the requirement.

No funds.

Bye.

Knock knock.

Hey. Funds not a problem.

Guts?

What if I lose?

Bye.

Knock knock.

I wish to invest and the risk is digestible.

Ok. Pull the trigger.

Should we wait for a better price?

Bye.

Knock knock.

Let’s pull the trigger.

Ok.

There.

Bye.

Hey, it’s been a month and I’m up 10%. Let’s cash out.

Ok. Bye.

Knock knock.

This time I’ll let my profit run. The last one doubled in 6 months, but I’d cashed out after a minuscule rise.

So you’ve learnt how to sit?

I keep a lookout for you. If I’m not home I get alerted to your presence, so that I can act in time.

Then, I always maintain ample liquidity for you.

The amounts I put in make my risk digestible, looking at the total size of my portfolio and liquidity.

Once you knock, I’m not afraid to pull the trigger anymore.

I’ve learnt to let multibaggers develop. I don’t nip them in the bud anymore.

Wonderful. Now add cost-free-ness to your repertoire.

Why?

It’ll trick your mind into holding your multibagger eternally, so that it is given the chance of becoming a megabagger.

Will do, thanks, cost-free-ness won’t cost me anything, right?

Not a penny.

Playing Over-hot Underlyings with the Call Butterfly

A call butterfly is a fully hedged options trade …

… with an upwards bias.

It consists of four call options.

2 buys…

…and 2 sells.

One can play any overtly rising underlying with the call butterfly, without batting an eyelid.

Why?

Firstly, and most importantly, one is fully hedged.

Meaning?

At first look, the call butterfly seems market neutral as far as basic mathematics is concerned, that is +1, -2, +1, net net 0.

So, net net, one isn’t looking at a large loss if one is wrong.

When is one wrong here?

If the underlying doesn’t move, or if it falls, in the stipulated period, then one is wrong,…

…and one will incur a loss.

However, the loss will be relatively small, because of the call butterfly’s structural market neutrality.

And that’s magic, at least to my ears.

Method to enter anything flying off the handle with the chance of a small loss?

Will take it.

Then, also very importantly, the margin requirement is relatively less, when one uses the following chronology.

One executes the buys first.

Then come the sells.

Upon the upholding of this chronology, the market regulator is lenient with one on margin requirement, as long as the trade-construct is market neutral.

Typically, for one butterfly, total margin requirement is in the range of 50 to a 100k.

Now let’s talk about what one is looking to make.

5k per single-lot trade-construct, if it’s fast, as in execute today, square-off tomorrow, or even intraday, if expiry is close.

10k if slow, as in 7 to 10 days.

If the butterfly is not yielding because the underlying is not moving, then one is looking to exit, typically with a minus of under 3k.

Just do the math. Numbers are great.

What kind of a maximum loss are we looking at, if things go badly wrong, as in if the underlying sinks?

5k to 10k.

Can the loss be more?

If the trade construct is such that the butterfly can even give 40 odd k till expiry, one could even be looking at a max loss of about 15k too.

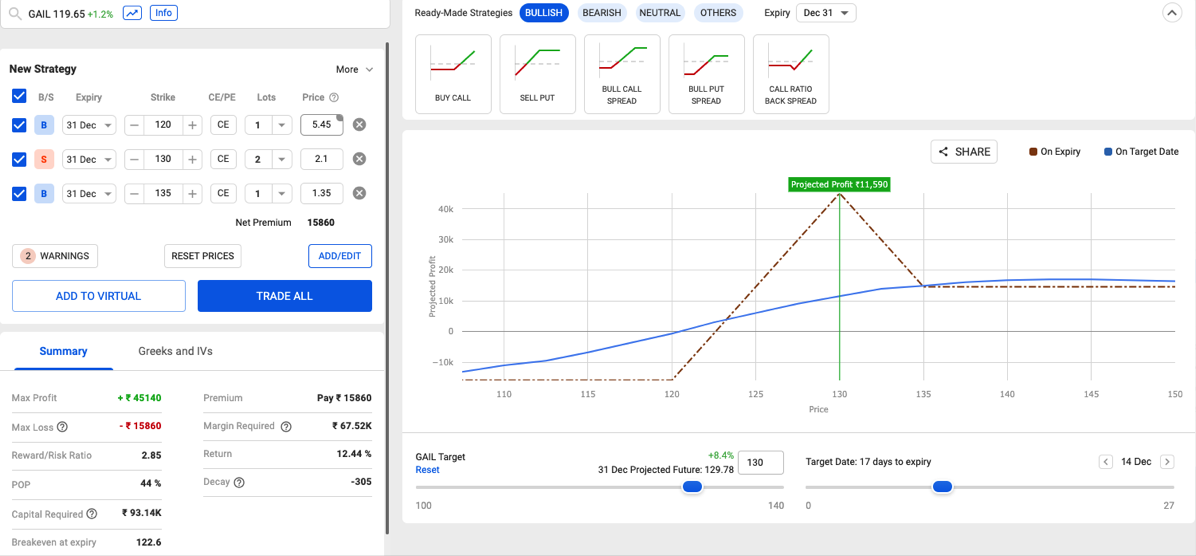
Here’s an example of a call butterfly trade that can lose around 15-16k, but has the potential to make upto around 45k till expiry. The graphical representation is courtesy Sensibull.

GAIL Call Butterfly Dec 31 2020 Expiry

I mean, it’s all still acceptable.

Tweaks?

Let’s say one is losing.

Sells will be in biggish plus.

Square-off the sells. Yeah, break the hedge.

Margin gets returned. Premium pocketed.

Buys are exposed, though.

They are losing big.

With some time to go till expiry, if the underlying goes back up, the buys gain.

What one makes off the trade is proportional to how much the underlying goes up.

It’s riskier. Correspondingly, profit potential is higher.

Money risked here will be up to double of the fully hedged version of the trade, and one could lose this amount if the underlying does not come back up appropriately and in time. Pocketed premium of the squared-off sells softens the hit.

Therefore, it makes more sense to pull this tweak with at least ten days to go before expiry, giving the underlying time to recoup.

Got another tweak.

This one’s intraday, though.

Underlying’s on a roll, and you want to make the most possible off the opportunity.

Square-off the sells at a huge loss.

Let the buys, which are winning big, run for some part of the day.

Chances of them yielding more are very high.

Square-off the buys before close of trade.

If the underlying promises to close on a high, square-off the out-of-the-money buy before close of trade, and take the in-the-money buy overnight.

Risky, though.

You could lessen your risk, and increase your chances of taking most profits off the table by squaring off the in-the-money buy and taking the out-of-the-money buy overnight.

Square-off the overnight buy next morning on a high, or wherever feasible.

With this particular tweak, the trade becomes somewhat more like a lesser exposed futures transaction, at least for some time, after the hedge is broken.

There’s another thing one can do with the call butterfly.

One can adjust it as per the level of perceived bullishness.

If -1 and -1 are set at the same level, one trades for averagely perceived bullishness.

If one -1 is closer to the lower +1, and the other -1 is above this first -1, then one trades for below average perceived bullishness.

If one -1 is closer to the upper +1, and the other -1 is below this first -1, then one trades for above average perceived bullishness.

Anything else worth mentioning?

Volume. Need it.

Bid-ask spread needs to be narrow.

Scaling up needs to correspond to one’s risk-profile, requirement, temperament and acumen.

One can make it an income thing by scaling up, during bull runs, or generally, just in case an up move is tending to pan out.

One can make the call butterfly do a lot of things.

It’s a very versatile trade to play a rising market, with low risk and low capital requirement.

Happy trading!

🙂

Bonding

As Equity players…

…we enter the bond segment to…

…conserve capital.

There is no other reason.

Return?

We do make a slightly better return than a fixed deposit.

We’re not in bonds to make a killing.

That is outlined for the Equity segment.

We’re Equity players, remember. 

I was just going through the top ten holdings of each of FT India’s now “discontinued” (new word for mini-insolvency?) debt funds. (I’m uncertain just now what word they’ve used, was it “stopped”? Or “halted”?) [Just looked up the internet, the words used are “winding up”].

My goodness! 

The fund managers in question wanted to outperform all other funds at the cost of asset-quality. 

Many of these top ten holdings (for six funds, one is looking at six top ten holdings) one would not even have heard of. 

A top ten holding constitutes the backbone of the mutual fund being studied. 

If the backbone is wobbly, the whole structure trembles upon wind exposure. 

This corona black swan is not a wind. It’s a long-drawn out cyclone, to fit the analogy. 

This particular structure has crumbled. 

Fund managers concerned have acted out of greed – that’s the only explanation for above top ten holdings. 

No other explanation comes to my mind. 

That they are also holding large chunks of Yes Bank and Vodafone is more an error in judgement, albeit a grave one. 

People commit errors in judgement.

Could one still overlook the a large chunk’s (10%?) segregation in FT India’s Debt folios, where Yes and Voda bonds have been marked down to zero?

Such a hit is huge in the debt segment.

Why are we in debt?

To conserve capital. 

10% hit in debt?

NO.

Wobbly top ten holdings?

NNOO!

Had no idea that the FT India debt portfolio had so many red-flags. 

Till they dropped the bombshell that they were discontinuing their six debt-funds, from last evening, one had no idea. 

Now that it’s dropped, one digs deep to understand their mistakes.

Why?

One doesn’t want to make the same mistakes. 

One doesn’t want to be invested in any funds in the debt segment which are making the same mistakes.

However, another look at their holdings reassures one that one won’t be making such mistakes, of greed, and of comprehensive failure to read managements and road conditions – in a hurry.

Nevertheless, one wishes to be aware.

Now that one is, all measures will be enhanced to prevent even an inkling of such an outcome for oneself. 

Wait up. 

Such measures were already in place. 

Greed? In bonds? 

We’re in bonds to conserve capital. 

No greed there. 

Top ten holdings?

Rock-solid. 

That’s the fundamental tenet one looks for while entering any mutual fund, whether in the debt or in the equity segment. 

We’re good. 

Frozen

Frozen? 

It’s ok. 

Breathe. 

You need to acknowledge that you’re frozen. 

Without that, the next step won’t come. 

It’s normal to freeze sometimes. Just acknowledge it. Then learn. 

For example, I acknowledge that I’m currently frozen wrt to the USDINR short trade. Missed entry. Next opportunity to enter never developed for me, and the underlying is currently in free fall. Don’t have the guts to short it at this level. Yeah, I’m frozen all right.

However, the fact that I’m acknowledging it opens up the learning window. 

Why did I miss entry?

I know why I froze. Fear. What I need to understand is why I allowed a situation to develop that would lead to fear. 

Ok. 

Was running super busy. 

Neglected the underlying. 

Kept postponing entry… 

… till free-fall started. 

It’s good to be busy. 

Hmmm, so this can happen again. 

How do I stop this from happening again? 

If I ID a setup, I need to take it. 

No second-guessing. 

What about strategy? 

Meaning, am I going with a short strategy for USDINR? Or am I keeping the window open for a long strategy?

See, that’s it.

Keeping short and long windows open makes me second-guess all the time. 

So can I go in one-direction wrt USDINR all the time? 

What speaks for it? 

Underlying is falling from a height. Good. 

Short only means no second-guessing. You just go short, period. 

Stoploss will save ruin. 

Not nipping profits in the bud will amass fortunes. 

Can the underlying keep falling over the next few years? 

Why not? Modi’s looking set for 2019. 

Hmmm, so a short only strategy has a lot going for itself. 

There’s more. Future month contracts are quoted at a premium. The premium evaporates over the current month. This move is in your favour if you’re short. 

Ok, enough. 

Yeah, there’s enough on the table to warrant a short only strategy for USDINR. 

SEE? 

Learning process. 

Why did it happen?

Because I acknowledged that I had frozen. 

Now, my strategy is more fine-tuned and I’m probably less prone to second-guessing. 

You need to pull off such stuff when you freeze. 

Use the freeze to evolve.